Income Tax Act 2025 Explained for Small Businesses & Salaried Taxpayers
If you have been hearing “new Income Tax Act” for months and quietly hoping it does not affect you, you are not alone. A lot of salaried employees and shop owners in Delhi NCR have the same feeling: I filed my return last year, so what exactly is different now?
Here is the short version. The law got a makeover, but your tax bill did not get a surprise. Let’s walk through what is new, what is not, and what you should actually do about it.
The Quick Answer
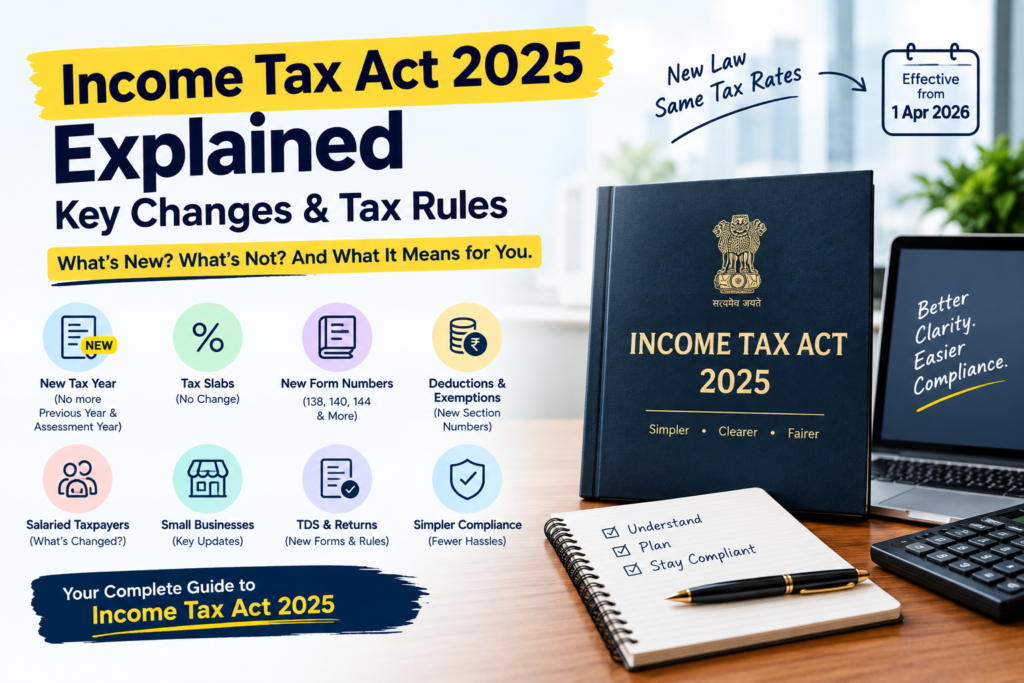
What is the Income Tax Act 2025? It is India’s new income tax law. It replaces the Income-tax Act, 1961 and has applied since 1 April 2026. It is a cleaner, shorter rewrite, not a new tax policy.
Do my tax rates change? No. Budget 2026 did not change slabs, surcharge or cess for tax year 2026-27, and the new tax regime remains the default.
Does it affect me right now? Income earned from 1 April 2026 onwards falls under the new Act. Income up to 31 March 2026 is still handled under the old one.
That last line matters more than it sounds, so we will come back to it.
Why Was a New Act Needed?
The 1961 Act had been patched and amended for over sixty years. It had 819 sections. Reading it was like reading a house that had been extended room by room without a floor plan.
The new Act has 536 sections and 16 schedules. Sections were reorganised, definitions were brought together, and the language was simplified. Things like PAN, TDS, faceless assessment, deductions, capital gains, business income and salary taxation continue in substance. Think of it as the same rulebook with a better index.
The Biggest Visible Change: “Tax Year”
For decades, we all juggled two terms: the previous year (when you earn) and the assessment year (when it is assessed). Every first-time filer got confused by it, and honestly, many experienced ones did too.
Now there is just one: the tax year. Income earned between 1 April 2026 and 31 March 2027 belongs to Tax Year 2026-27. That is it.
So if someone mentions “Tax Year 2026-27”, they mean the same 12 months you would have called FY 2026-27. No second label to decode.
Which Act Applies to My Return Right Now?
This is where people get tangled, so let’s keep it simple.
- FY 2025-26 (April 2025 to March 2026): taxed under the old Act, filed as AY 2026-27. If you are filing a return this season, this is the one.
- FY 2026-27 (April 2026 onward): taxed under the new Act, as Tax Year 2026-27.
So you may be dealing with both at the same time: finishing last year’s return under the old rules while your payroll or books for this year are already running on the new ones. That is normal. It is not a mistake on your side.
For Salaried Taxpayers: What Actually Matters
Your slabs and savings did not change
The new tax regime stays the default, with the same slabs. The standard deduction for salaried people remains ₹75,000 under the new regime (₹50,000 under the old). With the rebate, a salaried person’s income of around ₹12.75 lakh can come out with no tax payable under the new regime.
If you were comfortable with your numbers last year, you will most likely be comfortable this year.
Section numbers have changed
This is the part you will notice first. The deductions you know by heart, such as 80C and 80D, still exist, but they now carry new section references in the new Act. For example, 80C is now read with Section 123, and 80D with Section 126.
So when your CA says “Section 123”, do not panic. It is the same investment limit you already know, wearing a new name tag.
Your salary certificate has a new name
Form 16 is now Form 130 under the new framework. If your HR sends you a salary TDS certificate with a different form number this year, that is why.
You can still choose your regime
If you do not have business income, you can pick the old or new regime afresh each year when you file. There is no lock-in. If you have home loan interest, large insurance premiums and 80C investments, it is worth running both calculations before deciding rather than assuming the new regime always wins.
Revised returns have more breathing room
Recent guidance says the window to file a revised return has been stretched to 31 March of the following year, subject to a nominal fee. That gives you extra time to fix a missed deduction or a wrong figure, though it is still best to get it right the first time.
For Small Business Owners: What Actually Matters
If you run a shop, a small manufacturing unit, a clinic or a consultancy in Delhi NCR, here is what to keep an eye on.
Your books do not need a new system
Business income, expenses, depreciation and presumptive taxation continue in substance. You do not have to rebuild your accounts. What changes is the references in your documentation and returns.
TDS forms have new numbers
This one is practical and immediate. The familiar quarterly TDS returns are now Form 138 (salary), Form 140 (non-salary payments to residents) and Form 144 (non-residents). The Q2 return is due on 31 October. We have covered this in detail in our guide to the TDS return due date in October, so have a look if you deduct tax on salaries, rent or professional fees.
Check your accounting software
If your payroll or accounting software is not updated, it may still print old form names or old section numbers. Ask your vendor whether it has been updated for tax year 2026-27. A small update now saves a lot of explaining later.
Choosing your regime has more weight for business owners
If you have business or professional income and opt out of the default regime, switching back is generally limited. Do not choose casually. Sit down with your CA before filing, and look at the next few years, not only this one.
Old and new rules can overlap in the same year
Your tax audit, advance tax and return for last year may follow the old Act while this year’s TDS and day-to-day compliance follow the new one. Keep a simple note of which year each task belongs to.
What Did Not Change (and Why That Is Good News)
Because a new Act sounds scary, it helps to list what stayed the same:
- Your PAN and TAN
- The online filing process on the income tax portal
- The ITR forms’ basic data requirements for tax year 2026-27, with updated section references
- Deductions and exemptions in principle
- Faceless assessment and faceless appeals
- The need to file on time, and the cost of not doing so
In other words, the paperwork looks different, but the habits that keep you safe are the same: keep records, reconcile regularly, file on time.
A Simple Plan for the Next Few Weeks
You do not need to study the whole Act. A few small steps are enough.
- Know your year. Is the task about last year (old Act) or this year (new Act)?
- Collect your documents. Salary slips, Form 26AS, AIS, investment proofs, bank statements, rent receipts, and business ledgers.
- Look at both regimes. Especially if you have deductions. Do not guess.
- Check your TDS. Make sure what was deducted matches what shows in your records.
- Update your software. Payroll and billing tools should reflect tax year 2026-27.
- Ask early, not late. A 15-minute chat with your CA in October beats a rushed one on the last day.
Common Misunderstandings
“The new Act means new tax rates.” It does not. Rates and slabs are unchanged for tax year 2026-27.
“The 1961 Act is gone, so old cases don’t matter.” Assessments and appeals for earlier years continue under the 1961 Act.
“If section numbers changed, my deductions disappeared.” They did not. The section numbers moved, but the benefits are still there.
“I can ignore this until next April.” Not quite. The new Act is already in force for this year’s income and TDS.
Why This Matters in Delhi NCR
In places like East Delhi, Noida, Ghaziabad and Gurugram, a lot of income comes from salary, small trading, services and professional work. Many families have a mix: one member in a job, another running a shop, and a parent with rental or pension income. A rewrite like this touches all of them differently, which is why a one-size-fits-all checklist rarely works. The best approach is to look at your own mix of income and see which rules apply.
Frequently Asked Questions
1. What is the Income Tax Act 2025?
It is India’s new income tax law that replaced the Income-tax Act, 1961 from 1 April 2026. It simplifies the structure and language without changing the core tax policy.
2. Have income tax slabs changed under the new Act?
No. For tax year 2026-27, slabs, surcharge and cess remain unchanged, and the new tax regime is still the default.
3. What is a “tax year”?
It replaces the old “previous year” and “assessment year”. Income earned from 1 April 2026 to 31 March 2027 is simply called Tax Year 2026-27.
4. Which Act applies to the return I am filing now?
If you are filing for FY 2025-26 (AY 2026-27), the old 1961 Act applies. Income from 1 April 2026 onwards falls under the new Act.
5. Do small businesses need to do anything differently?
Mostly small things: use the new TDS form numbers (138, 140, 144), update accounting or payroll software, and be careful when choosing between the old and new regime, especially if you have business income.
Need a Hand With It?
Taxes are easier when someone looks at your numbers rather than the headlines. If you would like help comparing regimes, preparing your return or setting up TDS under the new forms, the team at Innovative Taxation in East Delhi is happy to help. Take a look at our ITR services or book a 30-minute consultation.
Disclaimer: This article is for general information and does not replace professional advice. Tax laws and section references may be updated, so please consult a qualified Chartered Accountant for your specific case.